· Education · RED Lending
Seasoning: How Long You Have Owned the Property Changes the Loan
Seasoning is how long you have owned a property, or how long ago a credit event happened. Here is how it can shape a loan and what to plan for.
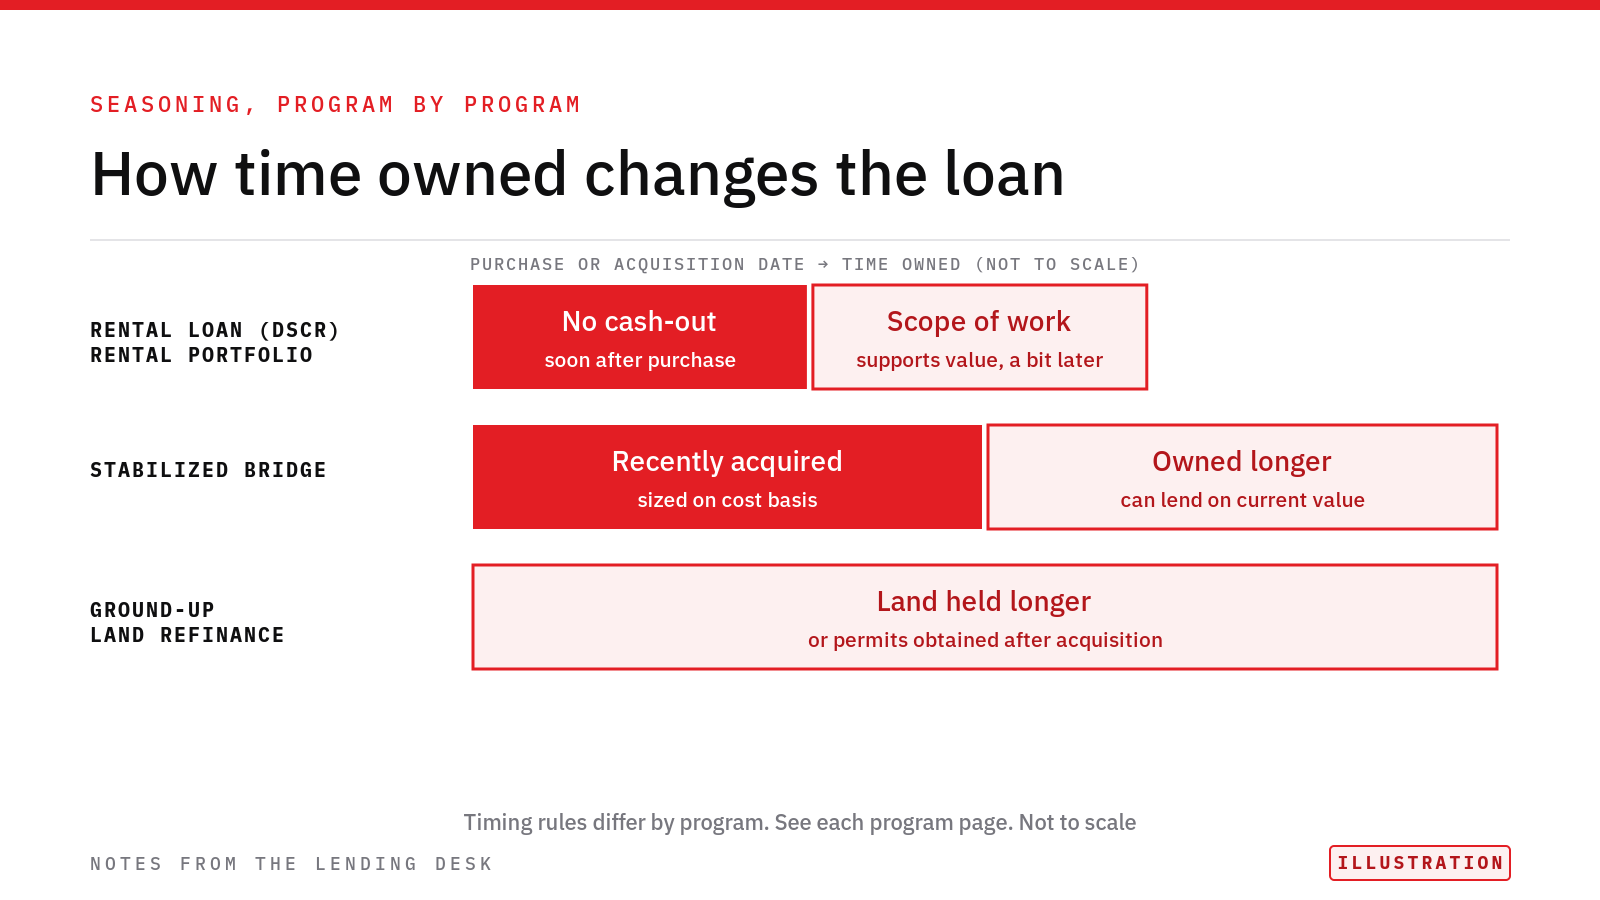
Seasoning is how long you have owned a property, or how long ago a credit event happened. Lenders use it to judge how reliable a value or a credit history is. Several loan terms can turn on it.
Why ownership time matters
A property bought recently has a known price: what you paid. If you ask a lender to use a much higher value soon after, the lender needs to see why the value went up. Time owned, completed work and good records all help.
Cash-out on a rental loan
On a Rental Loan (DSCR), cash-out soon after purchase is limited. In the period after that, expect to show a scope of work that supports the higher value. The scope of work shows what you did to the property. Without it, a quick jump in value is hard to support.
Bridge loans: cost basis or current value
On a Stabilized Bridge loan, time owned decides whether the loan is sized on what you have put into the property or on its current appraised value. With short ownership, the loan is usually sized on the purchase price plus verified completed work. With longer ownership, it can be sized on current value. A recent prior sale can also affect how the value is read, unless the renovation is documented and the appraisal is well supported.
Land for ground-up construction
When you refinance land you already own for a ground-up build, the desk looks at how long you have held the land and when the permits were obtained.
Credit events
Bankruptcy and foreclosure have their own seasoning. Each program sets how long ago the event must have been. A more recent event may still work on some programs with added conditions, such as an interest reserve.
Paperwork has a shelf life too
Appraisals and credit reports expire. An older appraisal may need a recertification of value. An older credit report may need to be pulled again. Check the dates on your documents before you submit.
Put it on one calendar
Before you close, put your purchase date, your renovation finish date and your target refinance date on one calendar. If a date sits close to a seasoning line, send the scenario and ask the desk how it reads. Specific timelines are set by program and confirmed deal by deal.
This post is general information, not financial, legal or tax advice. All loan terms are subject to underwriting and credit approval.