REDLending

A direct lender for brokers and wholesalers

Send us the file. Keep the relationship.

You are dealing directly with the lender of record. RED evaluates your client's scenario against available program parameters and remains your lender-facing point of contact through the transaction. Submit on your client's behalf and stay on the deal: every question comes back through you.

Named
Broker of record
Six
Loan programs
12 mo – 30 yr
Terms

Business-purpose loans against non-owner-occupied 1–4 unit residential investment property in 37 states and the District of Columbia, and 5+ unit multifamily in 10 of them.

Programs

Every program, with the numbers on the page

Fix & Flip

Fix & Flip

Our flagship

Purchase and renovation, 12 months

Purchase and renovation financing for non-owner-occupied 1–4 unit residential investment property. Up to 90% of purchase price and up to 100% of the renovation budget.

90%
Max LTC
75%
Max ARV-LTV
100%
Of renovation budget
660
Minimum FICO
Full tear sheet
Rental Loan (DSCR)

Rental Loan (DSCR)

Thirty-year rental financing

Long-term financing against a single cash-flowing 1–4 unit rental. Qualification is driven by property cash flow, not personal income — no tax returns.

80%
Max LTV, purchase
75%
Max LTV, cash-out
1.05x
Minimum DSCR
30 yr
Term
Full tear sheet
Stabilized Bridge

Stabilized Bridge

Rent-ready, no renovation planned

Short-term financing against a recently renovated or newly built property that is listed for sale or about to be rented. No renovation budget, no scope of work.

85%
Max LTC
70%
Max LTV
1.10x
DSCR exit option
12 mo
Term
Start a conversation
Multifamily 5+

Multifamily 5+

Small balance transitional bridge

Bridge financing against a single 5+ unit residential multifamily property being repositioned. Light to moderate renovation only, and a narrower footprint and sponsor profile than the rest of the platform.

70%
Max LTC
75%
Max LTV, as-is
1.25x
Stabilized DSCR
725
Minimum FICO

Experience is required — first-time multifamily buyers are not eligible — and the guarantor carries liquidity of 10% and net worth of 100% of the loan amount. Single properties only; no mixed use.

Start a conversation
Ground-Up Construction

Ground-Up Construction

Infill builds, by conversation

Construction financing for 1–4 unit infill development on single lots and small schemes. This one starts with a call rather than a quote: it is experience-gated, permit status moves the leverage, and the desk would rather talk it through than price it from a form.

75%
Max LTC, permitted
70%
Max ARV-LTV
90%
Max loan to final cost
680
Minimum FICO

Tier 3 experience and 680 FICO minimum, and leverage drops from 75% to 60% of land value without permits in hand. Infill lots only — no large tracts, rural or remote sites.

Start a conversation
Rental Portfolio

Rental Portfolio

One loan across many doors

Blanket financing against a collection of 1–4 unit rentals. One loan, one closing, one payment, underwritten on the portfolio's combined cash flow.

80%
Max LTV, purchase
75%
Max LTV, cash-out
1.05x
Minimum DSCR
2–10
Properties per loan

This is a 30-year loan, not a short-term facility — the same fixed and ARM structures as the single-asset rental loan, with partial interest-only available. Two to ten properties, $50,000 minimum per property, and 90% of the portfolio must be occupied by unit count. Leverage drops to 70% where a quarter or more of the portfolio is worth under $100,000.

Start a conversation

Pricing is quoted per deal — we publish no rate floor. Fix & Flip and Rental (DSCR) carry a published tear sheet. The rest begin with a conversation: their terms move with the sponsor and the site, and a number quoted before that discussion is not one we could stand behind. Multifamily 5+ also runs on a narrower footprint — CT, IL, MA, NC, NH, NJ, NY, PA, RI, SC only.

How it works

From your file to the closing table

  1. 01

    Submit on your client's behalf

    You are captured as the broker of record on the file. Your client's details sit under yours, not beside them.

  2. 02

    Preliminary review

    RED reviews the scenario against program parameters. Questions come back to you, and you decide what reaches your client.

  3. 03

    Indicative terms through you

    We quote to you. You present it. We do not go around a broker who brought us the deal.

  4. 04

    Close, with your fee agreed

    Compensation is settled with the desk on the file. We do not publish broker economics on a website, and we do not quote your client a number you have not seen.

Scenarios are reviewed by the desk in the order they arrive, and we come back with terms or with questions.

Who we lend to

What the desk needs to be true

An entity, not an individual

An LLC or corporation must hold title. Nonprofits and charitable organizations are not eligible. At least 51% of the entity guarantees the loan.

Business purpose only

Non-owner-occupied residential investment property — 1–4 unit across the footprint, and 5+ unit multifamily in selected markets. If anyone intends to live in it, this is the wrong lender.

Experience helps, but is not required

First-time investors are eligible, capped at a $100,000 renovation budget and 25% of purchase price. Experienced sponsors price and lever better.

Credit is a floor, not a score

660 minimum FICO, with 600 to 660 considered case by case. Foreign nationals are eligible with a valid passport, a valid US visa, and US credit where a personal guaranty is used.

What we need from you

The submission checklist, up front

Fix & Flip

  • Property address, purchase price and executed contract
  • Scope of work with line-item renovation budget
  • Borrower track record — last three years of investment properties
  • Guarantor FICO and entity formation documents
  • Architect letter or permits where square footage is being added

Rental Loan (DSCR)

  • Property address and purchase contract or original HUD / deed
  • Executed leases for all occupied units, plus proof of rent collection on refinances
  • Two consecutive months of bank statements from a single account
  • Tax certificate, insurance certificate and HOA fee documentation
  • Entity documents and guarantor credit authorization

Collateral

What qualifies, and what does not

Eligible

  • Single family residence
  • 2–4 unit multifamily
  • Condominiums
  • Townhomes
  • Planned unit developments
  • Non-owner occupied only

Not eligible

  • Mixed use
  • 5+ unit multifamily
  • Condotels
  • Co-ops
  • Mobile / manufactured
  • Commercial
  • Cabins / log homes
  • Leasehold
  • Oil or gas leases
  • Operating farms, ranches, orchards
  • Vacation or seasonal rentals
  • Unique, exotic or luxury
  • Unpaved / dirt roads

Eligibility differs slightly between programs — the tear sheet for each carries its own list.

Why RED

Work directly with your lender of record

Work directly with your lender of record

RED is the direct lender and lender of record. Your loan documents are with RED, while specialized third-party providers support underwriting, credit review, funding administration, assignment, and servicing.

Priced to compete, per deal

Our pricing stands against anyone quoting the same file. We publish no rate floor because two deals at the same LTV are not the same risk — you get indicative terms for your deal rather than a range that fits nobody.

The requirements are published

Every program page carries its full term table, the collateral we will and will not lend against, and the exact submission checklist.

Every program, underwritten properly

Fix & Flip, Rental (DSCR), Stabilized Bridge, Ground-Up, Rental Portfolio and Multifamily 5+. Each one has published figures and a stated gate, because a program we cannot describe precisely is one we should not be offering.

One point of contact, start to finish

The person who reads your scenario stays with it through to closing and remains your point of contact. Nothing is handed to a queue.

A no is worth having early

If the scenario does not fit the program parameters we say so plainly, with the reason. A maybe that runs three weeks costs you the deal you could have placed somewhere else.

Where we lend

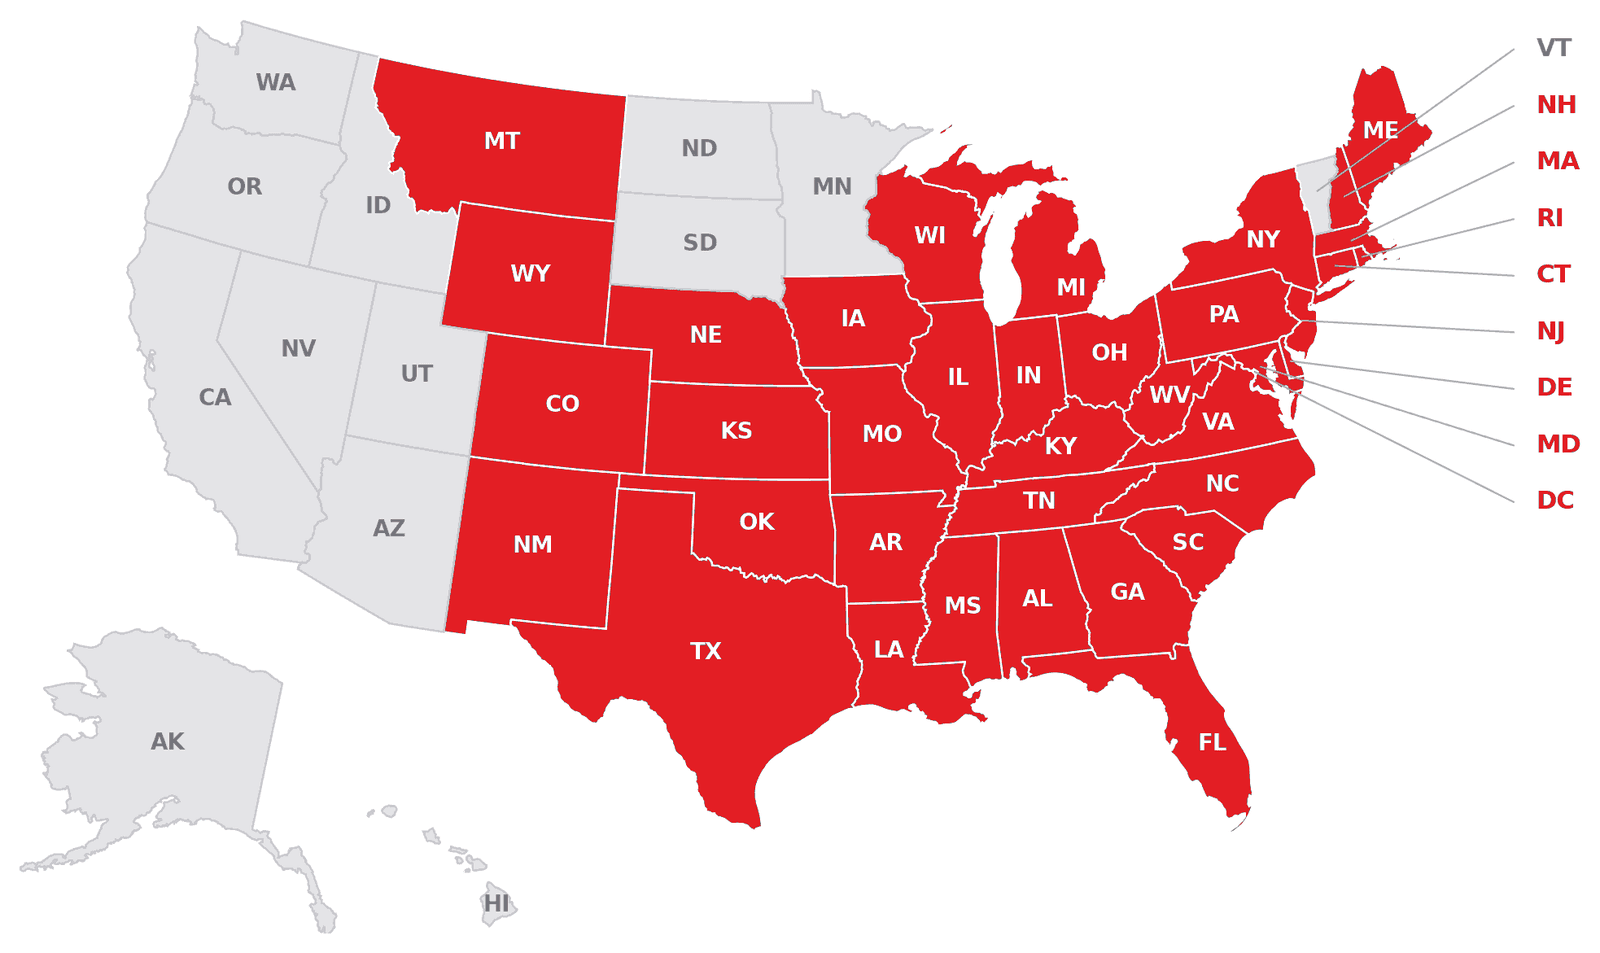
37 states and the District of Columbia

Map of the United States with the 37 states REDLending lends in, plus the District of Columbia, shown in red.
ALARCOCTDCDEFLGAILINIAKSKYLAMEMDMAMIMSMOMTNENHNJNMNYNCOHOKPARISCTNTXVAWVWIWY

Reduced leverage applies in FL and LA and in select counties. Four Florida counties (Lee, Charlotte, Sarasota, Collier) and Baltimore City are closed. Prepayment provisions vary by jurisdiction and transaction: several states prohibit a prepayment penalty outright and others cap it by loan size, term or property type, so the provisions available on a given loan are confirmed when the scenario is quoted.
Questions

The things people ask first

Is this a consumer mortgage?
No. Every loan is a business-purpose loan secured by non-owner-occupied residential investment property, and is not offered for personal, family or household purposes.
Do you need my tax returns?
Not on the Rental (DSCR) program — qualification is driven by the property's cash flow rather than personal income. Fix & Flip is underwritten on the project and the sponsor's track record.
Can I borrow in my own name?
No. An LLC or corporation must hold title, and at least 51% of the entity provides a personal guaranty.
Will you lend to a first-time investor?
Yes. First-time investors are capped at a $100,000 renovation budget and 25% of purchase price, and leverage improves as verified projects accumulate.
What does it cost?
We quote per deal rather than publishing a rate floor, and we expect to be competitive with anyone pricing the same file. Pricing follows the sponsor, the property and the leverage, and any figure quoted before underwriting is indicative rather than committed — a headline rate on a website is quoted to the strongest deal a lender has ever seen, and it is rarely yours.
Are you a direct lender or a broker?
RED is the direct lender and lender of record. Your loan agreements are with RED. Underwriting, credit review, funding administration, assignment, and servicing may be supported by third-party providers.
Can I borrow against a property I already own?
Yes. Cash-out is available on the rental and portfolio programs at lower leverage than a purchase, and the bridge program is built for a property that is already stabilised and listed or about to be rented.
Where do you lend?
Across the footprint listed below. Reduced leverage applies in some states and counties, and a small number of jurisdictions are closed.

Talk to the desk

Send the file. We will come back to you.

Monday to Friday, 9:00am – 5:00pm Central

6010 W Spring Creek, Plano, TX 75024