· Education · Sayasone Phongvichith
Stabilized Bridge or Fix & Flip: which loan fits the deal?
Two RED short-term loans, two different jobs. Here is how to tell whether your deal is a bridge or a flip.
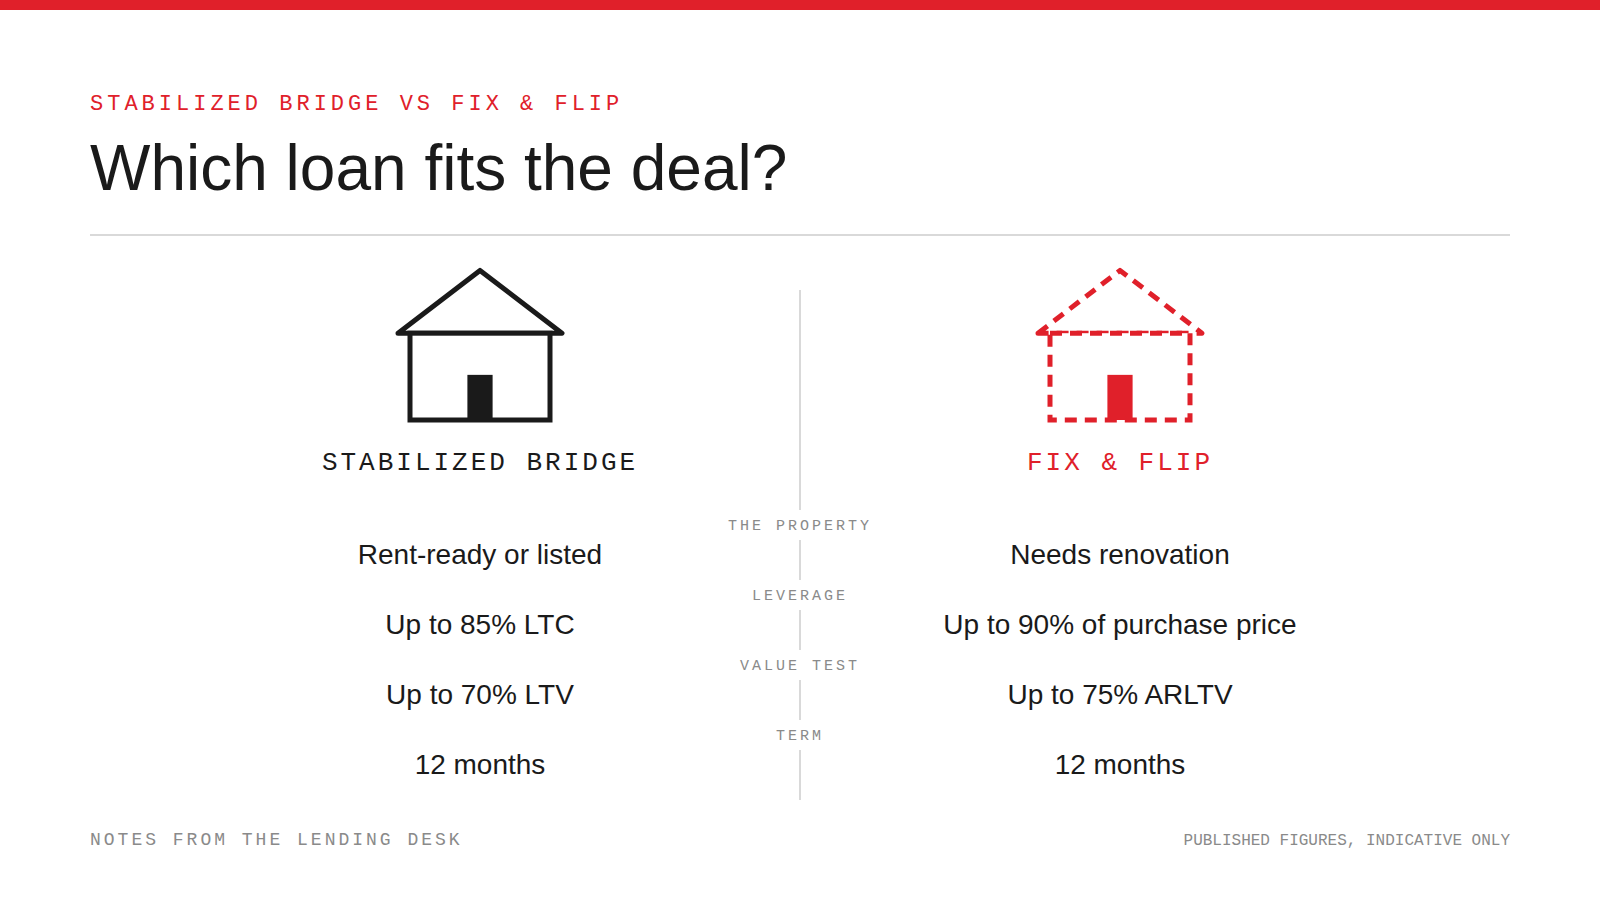
RED offers two short-term loans that can look alike on a first read. They are built for different jobs.
The one-line test
Does the property need renovation? If yes, start with Fix & Flip. If it is rent-ready or listed and no renovation is planned, start with Stabilized Bridge.
Fix & Flip
- For a purchase or refinance of non-owner-occupied 1 to 4 unit residential that requires renovation.
- Up to 90% of purchase price, plus up to 100% of the renovation budget.
- Up to 75% ARLTV (after-repair loan-to-value), with special requirements between 70% and 75%.
- 12 months. 18 to 24 months are available on expansion, addition, conversion and ADU projects, subject to a pricing adjustment.
- Minimum FICO of 660, with scores from 600 to 660 case by case. Experience is not required.
Stabilized Bridge
- For a purchase or refinance of a non-owner-occupied 1 to 4 unit property that is rent-ready or listed, with no renovation planned.
- Up to 85% loan-to-cost and up to 70% LTV. The initial loan is sized on the lesser of acquisition cost and as-is value.
- 12 months, with extensions of up to 50% of the original term for a fee.
- FICO of 660 for sponsors with three or more verified properties, 680 for sponsors with fewer.
Both programs are interest only with a balloon at maturity, and both run $50,000 to $1,000,000, with larger loans subject to an underwriter pre-screen.
A quick example of each
A dated house you will gut and resell: Fix & Flip. A leased duplex you are buying now and plan to refinance into a long-term rental loan: Stabilized Bridge.
What to send the desk
For Fix & Flip: the contract, a line-item scope of work and budget, and your track record. For Stabilized Bridge: the contract, the lease or listing agreement, and the last three years of investment property history. Pricing is quoted per deal.
Program figures are indicative only and subject to complete documentation, underwriting, appraisal and final credit approval. This post is general information, not financial or legal advice.